Nobody buys insurance hoping to use it. Then one day something happens — a fender bender, a burst pipe, a hospital bill — and suddenly you need to file a claim, even though nobody ever taught you how. The good news is that it is mostly about doing things in the right order, writing things down, and not throwing anything away.
What to Do First After an Incident
Start with people and safety. If anyone is hurt, call emergency services right away. After a car accident, move to a safe spot if you can, switch on your hazard lights, and check on everyone involved. In a home emergency, shut off the water or power if there is a burst pipe or electrical risk.
Next, stop the damage from getting worse. Insurers call this mitigating further damage, and most policies expect it. Put a tarp over a damaged roof or have a car towed rather than driving it with a leaking radiator. Keep receipts for what you spend — those costs may be part of your claim.
If another person is involved, exchange names, phone numbers, and insurance details calmly. Do not argue about fault or admit blame before you know the full picture. If police attend, note the report number.
Document Everything
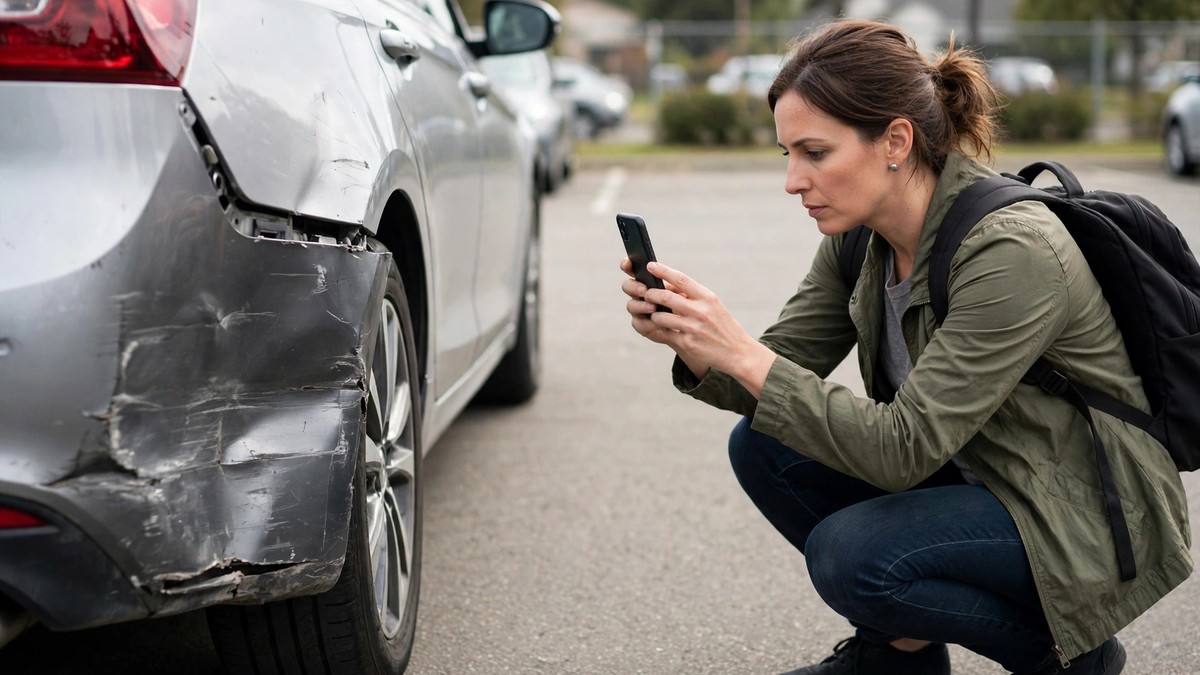
Good documentation is what separates smooth claims from frustrating ones. Photograph and video the damage from several angles — wide shots of the whole scene plus close-ups. For a car, capture all four sides, the plates, and the odometer. For a home, photograph each affected room. For medical claims, keep every bill and statement.
Write down what happened while it is fresh: date, time, location, and who was there. Note any witnesses and their contact details. Make a simple list of damaged items with approximate values — a rough list made today beats a perfect list you never write. Do not throw damaged items away until your insurer has seen them, unless they are a health hazard.
Contact Your Insurer and Have Your Information Ready
Once things are under control, contact your insurer as soon as you reasonably can — most policies ask you to report promptly. You can usually start a claim by phone, app, or website. Before you call, gather:
- Your policy number and the name on the policy
- The date, time, and location of the incident
- A short, factual description of what happened
- Photos or videos you have taken
- Contact details for anyone else involved, plus any police report number
The person who takes your call will open a claim file and give you a claim number — write it down at once, with the name of the person you spoke to. An adjuster will usually be assigned within a few days. If you are unsure whether something is covered, call anyway — Homeowners Insurance: What It Covers and What It Doesn't is a useful refresher for home claims. Do not assume a claim is not covered; let the insurer review it.
Working With the Adjuster
Your adjuster investigates the claim, estimates the damage, and recommends what should be paid. They may visit in person, ask for photos, or send a specialist. Be honest and specific, and stick to what you know. Share your photos, receipts, and notes. If you are unsure about something, say so — guessing causes more trouble than admitting you do not remember. Ask about next steps, and read anything you are asked to sign before you sign it.
Getting Repair Estimates
In many car and home claims you will need repair estimates. Your insurer may suggest preferred shops, but in many cases you may choose your own — check your policy or ask your adjuster. Get every estimate in writing, with the work itemized, and get more than one for larger repairs. If they differ widely, ask the contractors to explain why.
Do not authorize major repairs before the adjuster has inspected the damage, unless emergency work is needed — then photograph first and keep every invoice. If your claim involves a car, Full Coverage vs Liability Only Car Insurance: What's the Difference? explains what each type of coverage pays for, and How Much Car Insurance Do You Really Need can help you review your limits later.
Keep Records of Every Conversation
A claim can mean many phone calls, emails, and appointments. Keep a simple log — notebook, notes app, or spreadsheet — noting the date, who you spoke to, and what was promised. Save every email, letter, and text you receive, and copies of what you send. If something important is agreed on the phone, follow up with a short email: "Just confirming we agreed that…" That written record is invaluable if the claim drags on.
Understanding Your Deductible and Payout
Your deductible is what you pay before insurance starts paying. With a $500 deductible and $2,000 of covered damage, your insurer generally pays $1,500. If the damage costs less than your deductible, the claim may pay nothing. Your payout also depends on policy limits and whether coverage pays replacement cost or actual cash value. Replacement cost covers a new item of similar kind and quality; actual cash value subtracts depreciation. Your policy states which applies.
Before accepting a settlement, read the breakdown: what is covered, what was deducted, and whether more may follow if repairs uncover hidden damage. If something does not add up, ask first. Claims can sometimes affect your premium at renewal — Why Did My Insurance Premium Go Up? 7 Common Reasons explains the common reasons.
What to Do If a Claim Is Delayed or Denied
If your claim stalls or is denied, first find out why — ask your adjuster for a clear explanation in writing. A delay may mean the insurer is waiting for a document or inspection, which you can often help with. A denial should cite a specific part of your policy — read it alongside your policy, since the cause is sometimes a misunderstanding, like a missing form or a wrong date.
If you believe the denial is wrong, appeal with your evidence: what happened, what the policy says, and what supports you. If that fails, your state's department of insurance can explain your rights and may help mediate. Stay polite but persistent.
How the Steps Differ for Auto, Home, and Health Claims
The steps above fit most claims, but details shift by type. Auto claims move fastest when damage is straightforward and fault is clear. Home claims often take longer, involving contractors and inspectors. Health claims often start with your provider filing for you; your job is to review the explanation of benefits for errors. Health Insurance Plans Explained: HMO, PPO, HDHP, and EPO explains plan types, and Renters Insurance Explained covers the basics for renters.
| Claim Type | First Thing to Do | Key Documents to Keep |
|---|---|---|
| Auto | Make sure everyone is safe and exchange information | Photos of all vehicles, police report, repair estimates |
| Home | Stop further damage safely, such as shutting off water | Photos of each room, receipts for damaged items, contractor estimates |
| Health | Get the care you need, then check whether the provider is in network | Itemized bills, explanation of benefits, referral letters, prescription receipts |
Frequently Asked Questions
How long do I have to file an insurance claim?
It depends on your policy, state, and claim type. Many policies ask you to report promptly. Contact your insurer as soon as you safely can — waiting can make it harder to prove what happened.
Do I need a police report to file a claim?
Not always. A police report is commonly needed for car accidents, theft, and vandalism, but many home and health claims do not require one. File one whenever a crime, injury, or another driver is involved.
Should I file a claim for a small amount of damage?
It depends on your deductible and the repair cost. If the damage costs less than your deductible, your insurer pays nothing. Get an estimate first, then decide.
What if I disagree with the adjuster's estimate?
Ask for a written breakdown and compare it with your own contractor's or mechanic's estimate. Point out specific differences, or use your policy's dispute or appraisal process.
Can I choose my own repair shop or contractor?
In many cases, yes. Insurers often have preferred providers, but your policy and state rules decide whether you must use them. Ask your adjuster first.
Will filing a claim raise my premium?
It can, but not always. It depends on the claim type, fault, your claims history, and your insurer. A single not-at-fault claim often has less impact than an at-fault accident.
Filing a claim is rarely anyone's idea of a good time, but it does not have to be a mystery. Take care of safety first, document what happened, report the claim promptly, and keep a record of every step. For more plain-language guides, start at the homepage and browse the topics that match your situation.
Disclaimer: This article is general information only and is not financial advice. Insurance coverage, claim processes, and timelines vary by insurer, policy, state, and claim type. Always follow your own policy terms and talk to a licensed insurance agent or advisor about your specific situation before making a decision.