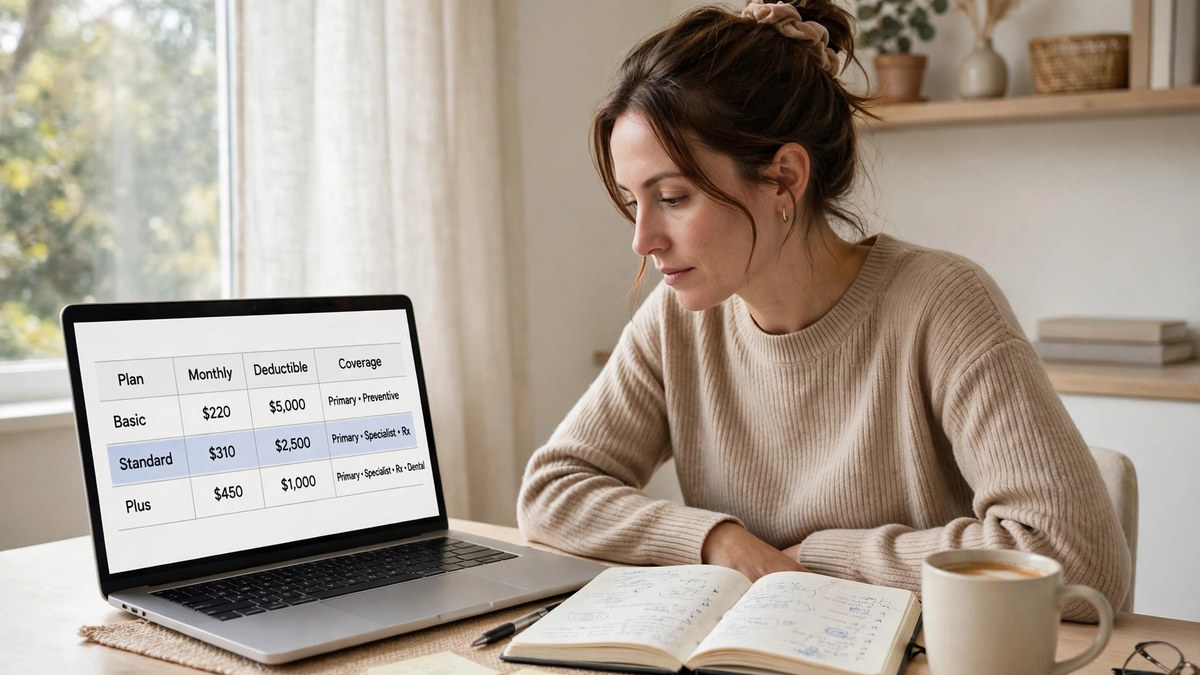
Shopping for health insurance can feel like reading a contract in another language. Premiums, deductibles, copays, networks, metal tiers — the words pile up fast, and the stakes feel high, because the plan you pick decides what a doctor visit costs you for months to come.
The good news: you don't need to become an insurance expert to make a solid choice. You just need a clear way to compare your options and a few questions to ask before you enroll. This guide covers what the Marketplace is, how the metal tiers work, how financial help is calculated, and how to look past the monthly premium to the number that really matters — your total cost. Our home page also gathers plain-English guides on car, home, life, and more.
What Is the Health Insurance Marketplace?
The Health Insurance Marketplace is an online service — run by the federal government or your state — where you can shop for health plans, compare them side by side, and find out whether you qualify for financial help. Every plan sold there meets the same basic standards.
It's mainly for people who don't get affordable coverage through a job: freelancers, part-time employees, people between jobs, early retirees, and anyone whose employer plan is too expensive or doesn't cover the family. If your employer offers a plan, you can still browse Marketplace plans, but you usually won't qualify for subsidies if your job-based coverage counts as affordable.
Every Marketplace plan covers the same essential health benefits: doctor visits, hospital stays, emergency care, prescription drugs, lab work, maternity and newborn care, mental health services, and preventive care like vaccines and screenings. Preventive services are typically free with an in-network provider. Plans differ in price, cost-sharing, and network — not in whether the basics are covered.
Health insurance is only one piece of the puzzle. Many families also ask how much life insurance they need, or weigh term life versus whole life, before their safety net feels complete.
Metal Tiers, Explained in Plain English
Marketplace plans are sorted into four metal tiers: Bronze, Silver, Gold, and Platinum. The metal says nothing about care quality — it describes how you and the insurer split the cost of covered services, on average.
It's a trade-off between monthly cost and cost at the doctor's office. Bronze usually has the lowest monthly premium and the highest deductible — the amount you pay before the plan starts sharing costs. Platinum flips that: a higher premium, but a much lower deductible and lower copays.
Silver sits in the middle, and it's the tier most people compare most carefully, partly because some financial help only applies to Silver plans. Gold is a step up: higher premiums, lower out-of-pocket costs.
| Metal Tier | Monthly Premium | Deductible | Best For |
|---|---|---|---|
| Bronze | Lowest | Highest | Healthy people who rarely see a doctor and want low monthly costs |
| Silver | Moderate | Moderate | Most shoppers; the only tier eligible for extra cost-sharing help |
| Gold | Higher | Lower | People who see doctors regularly or take ongoing prescriptions |
| Platinum | Highest | Lowest | People with frequent care needs who want predictable, low visit costs |
Which tier fits you depends less on your age than on how often you use care. Rarely see a doctor and mainly want protection against a big bill? Bronze can make sense. Chronic condition or regular prescriptions? Gold or Platinum may cost less over the full year.
Premium Tax Credits and Cost-Sharing Reductions
One of the biggest reasons to shop on the Marketplace is financial help — and many people qualify for more than they expect.
A premium tax credit lowers what you pay each month, based on your estimated household income, household size, and where you live. You can have it applied to your monthly bill or claim it later at tax time. Estimate income carefully: earn more than you estimated and you may pay some of the credit back; earn less and you may get extra back.
Cost-sharing reductions are a second kind of help, and they only apply to Silver plans. If your income falls within a certain range, they lower your deductible, copays, and out-of-pocket maximum — the most you'd pay in a year for covered care. A Silver plan with these reductions can sometimes beat Gold on value, so compare them before deciding.
Eligibility, subsidy amounts, and prices vary by income, household, state, and plan. The only way to know what you'd pay is to enter your information on the Marketplace and see your real quotes.
How to Compare Total Cost, Not Just the Monthly Premium
The monthly premium is the number that jumps out first — and the number most likely to mislead you. A low-premium plan can cost far more over the year if it has a high deductible and you actually need care.
Instead, estimate your total cost: the monthly premium times twelve, plus what you'd likely pay out of pocket for the care you expect. Add up your prescriptions, the doctor visits you know you'll have, and any planned procedures, and run those numbers through each plan. The Marketplace's comparison tools can help.
Three numbers matter most. The deductible is what you pay before the plan starts helping. The out-of-pocket maximum is the ceiling — once you hit it, the plan pays the full cost of covered services for the rest of the year. The copay or coinsurance is what you pay per visit after the deductible: a copay is flat, coinsurance is a percentage.
Rule of thumb: rarely use care, and a low-premium, high-deductible plan often wins. Use care regularly, and a higher-premium plan with a lower deductible often wins. Curious about the forces behind the price? Read about why insurance premiums go up.
Will Your Doctor and Prescriptions Be Covered?
A plan is only a good deal if it covers the care you actually use. Before you enroll, check two things: your doctors and your prescriptions.
Every plan has a network — the doctors, hospitals, and pharmacies that work with that insurer at negotiated rates. Seeing an out-of-network provider can cost far more, and in some plan types it may not be covered at all. Check the plan's provider directory for your doctor, your specialists, and your preferred hospital. Our guide to health insurance plans — HMO vs PPO vs HDHP vs EPO explains how networks and referrals differ.
Then check the plan's drug list, often called a formulary. Look up each prescription you take and see what tier it's on and what your copay would be. A drug that's cheap on one plan can be expensive — or uncovered — on another.
If you have a doctor or medication you can't give up, let that narrow your choices first and price second. Once you're covered, learn how to file an insurance claim before you ever need to.
Enrollment Periods: When You Can Sign Up
You can't buy a Marketplace plan at any moment. For most people, the main window is Open Enrollment, several weeks in the fall when anyone can enroll in or change a plan. Miss it and you generally wait until the next one — unless you qualify for a Special Enrollment Period.
A Special Enrollment Period opens after a qualifying life event: losing other coverage, getting married, having a baby or adopting, moving, or a change in household income. Most give you a limited window — often around 60 days after the event — so don't wait.
Some people can enroll at other times too, and Medicaid and the Children's Health Insurance Program accept applications all year.
A Simple Checklist for Picking a Plan
When you're ready to decide, run through this list:
- Estimate your income and household size honestly, and see what subsidies you qualify for.
- Check whether your doctors, hospital, and prescriptions are covered.
- Add up your total yearly cost — premium plus expected out-of-pocket costs — not just the monthly bill.
- Compare Silver with cost-sharing reductions against Gold before you pick a tier.
- Check the out-of-pocket maximum, so you know your worst-case year.
- Confirm the plan's network type and whether you need referrals to see specialists.
- Save or print the plan summary before you enroll.
If two plans look close, the one with your doctors in network and your prescriptions on a cheaper tier is usually the better pick.
Frequently Asked Questions
Do I have to buy health insurance through the Marketplace?
No. You can buy directly from an insurer or through an agent. But premium tax credits and cost-sharing reductions are only available through the Marketplace, so for many people it's the cheapest way to get covered.
What happens if I miss Open Enrollment?
You'll generally wait for the next Open Enrollment unless you qualify for a Special Enrollment Period after a life event like losing coverage, moving, or having a child. Medicaid and CHIP accept applications at any time.
Is a Bronze plan a bad plan?
Not at all. Bronze plans cover the same essential benefits as other tiers — the difference is how costs are split. A Bronze plan can be a smart choice if you're healthy, rarely use care, and want the lowest monthly premium.
Can I change plans after I enroll?
Usually only during Open Enrollment or a Special Enrollment Period. That's why it's worth comparing carefully before you commit.
What if my income changes during the year?
Report the change to the Marketplace as soon as you can. Your subsidy is based on estimated income, and updating it keeps your premium accurate and helps you avoid owing money back at tax time.
The information in this article is general information only. It is not financial, tax, or medical advice, and it may not reflect the rules, plans, or prices available in your state. Eligibility, subsidies, and premiums vary by income, household, state, and plan. Before you enroll, check the details of any plan you're considering on the Health Insurance Marketplace (HealthCare.gov) or with a licensed insurance agent who can review your situation.